

Experian®
by Experian
4.7
- Safety
- 100% Safe
- Category
- Finance
- Ratings
- 4.7
- Price
- Free
- Download
- 10.00M
This app is secure, reliable, free to install, and offers fast downloads without any risks or malware.
Screenshots
 Analysis by Getfullapps
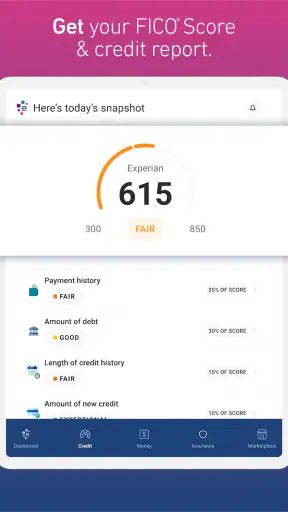
I found Experian® most useful when I treated it as a personal credit-and-finance workspace rather than as a complete household money manager. That distinction matters. The app is free, comes from Experian, and is aimed at helping one person keep an eye on credit-related information and financial habits from a phone. In my experience, it can make an otherwise vague subject feel more manageable, especially when I want a quick check before applying for something important.
It is also easy to imagine the app being used around a shared household. One person may be comparing borrowing options, another may be trying to understand why a credit profile changed, and both may want a clearer conversation about upcoming financial decisions. Still, the account itself should be treated as personal. I would not hand my signed-in session to another household member or assume that a shared device turns separate financial lives into one combined dashboard.
How Experian® fits into everyday household money decisions
A realistic use case is a couple preparing for a move. One partner checks the app before discussing a new card or loan, notices that the credit picture deserves attention, and brings that information into the conversation. The other partner can then review their own situation separately instead of relying on a screenshot or a remembered number. That small boundary prevents a common mistake: treating one person’s credit profile as if it represents the whole household.
I like this approach because financial coordination does not require sharing every login. A household can agree on goals, dates, and spending priorities while each adult keeps control of their own Experian account. The app becomes a prompt for better conversations, not a replacement for them. It is particularly practical when one person normally handles bills and the other wants a simple way to stay informed without asking for access to someone else’s financial details.
The app sits in the finance category, but it is more focused than a traditional budgeting tool. A budget app usually begins with transactions, categories, and monthly limits. Experian’s value is closer to credit awareness and monitoring. If your main question is, “Where did my money go this month?” a dedicated budget tracker may be the better first choice. If the question is, “What should I understand about my credit before making a major decision?” this app is more directly relevant.
That difference is one of the most important things to understand before installing it. I would not expect it to replace a bank app, a bill calendar, or a shared spreadsheet. Instead, I see it as one layer in a broader financial routine. The bank app shows cash movement, a budgeting tool organizes spending, and this app helps keep credit-related awareness in view.
Starting with the right personal boundary
Setup is easiest when I approach it as an individual financial check-in. I would use my own details, my own device profile, and my own login habits rather than creating a household account around a shared email address. That may feel less convenient at first, but it keeps the information tied to the person it describes. It also makes later conversations more accurate because everyone is looking at their own profile.
Articles to Explore Next

Uber Eats Makes Dinner Easier to Manage, but the Fees Add Up

Google Photos Turns a Camera Roll Into a Library You Can Find Your Way Through

Canva on Mobile: Adopt It for Quick Visuals, Test It for Demanding Work

Google Drive Keeps Work Moving Until It Doesn’t

Switching to Weather - By Xiaomi Means Relearning Your Forecast Routine

Ludo King and the Social Life of a Lucky Six
On a shared tablet or family phone, I would be especially careful about leaving the session open. Credit information is not the sort of material I want casually visible to children, visitors, or another person picking up the device. A household can share the hardware while keeping financial access separate. The practical rule is simple: use the app together only when the account owner is present, and sign out or lock the device when the check-in is over.
I also recommend deciding what you actually want to learn before opening the app. A focused visit might be about reviewing a recent change, preparing for a conversation with a lender, or building a regular credit-awareness habit. Without a clear question, finance apps can encourage endless checking without a useful next step. Experian® works better when I connect each visit to an action, such as checking a statement, reviewing a payment plan, or postponing an application until I understand the situation.
One useful household habit is to separate observation from decision-making. I might look at my credit information privately, then tell my partner only the part needed for a shared decision. For example, we may need to agree whether to delay a large purchase, but we do not necessarily need to exchange every account detail. This keeps coordination respectful and reduces the pressure to make personal financial information communal by default.
What the app is good at, and where alternatives win
Compared with checking a bank app alone, Experian gives me a different perspective. A bank app is excellent for current balances and transactions, but it does not serve the same purpose as a credit-focused service. Compared with a paper file or occasional manual check, the phone-based format is more convenient for routine awareness. The trade-off is that the app still requires interpretation: seeing information is not the same as knowing which action is sensible.
Compared with a general-purpose budgeting app, the experience feels narrower and therefore easier to approach when credit is the immediate concern. A budgeting app may be better for shared household planning because categories, bills, and spending targets are naturally discussed together. I would choose Experian when the decision depends on understanding my individual credit position, and I would choose a budgeting tool when the decision depends on coordinating everyday cash flow.
That narrower focus is also a limitation. Someone looking for one place to manage investments, divide bills, track subscriptions, and plan meals will probably find this app incomplete. I would not install it expecting a full family finance command center. Its strength is being a dedicated credit-and-finance reference point, not an all-purpose replacement for every financial tool on a phone.
Another trade-off is emotional. Credit information can make people anxious, especially when a household is already under pressure. Frequent checking may reassure one person while making another feel watched or judged. I found that the healthiest use is scheduled and purposeful: review the information, write down what needs attention, and then return to the actual financial task. The app should support calm decisions, not become a source of constant household tension.
Coordinating without merging separate accounts
For shared planning, I would create a simple routine outside the app. Each adult can review their own information, then bring only relevant conclusions to a short household discussion. The conversation might cover whether a planned application should wait, whether a payment date needs extra attention, or whether a larger purchase still fits the family plan. This gives the household coordination without pretending that everyone has the same credit history.
A second useful workflow is to keep a neutral decision log. Rather than recording sensitive account details, note the decision itself: “revisit the application next month” or “confirm the payment plan before applying.” This turns the app into an input for planning while keeping private information out of a shared notebook or messaging thread. It is a small but meaningful distinction for couples, roommates, and adult relatives who coordinate money without being financially identical.
I would also avoid using another person’s result as a benchmark. Two members of the same household can have different histories, obligations, and timing. Comparing them can create more confusion than clarity. The better question is whether each person understands their own position and knows the next sensible step. That is where the app is most helpful: it can encourage individual awareness while the household handles shared goals separately.
When a child uses the same device, I would keep the financial session clearly adult-only. The app has an Everyone content rating, but that should not be confused with a recommendation to give children access to an adult’s financial account. The rating describes the app’s content classification; it does not remove the need for account boundaries or age-appropriate supervision.
Age, trust, and shared-device expectations
The Everyone rating makes the app broadly accessible from a content perspective, and the minimum operating-system requirement is Android version 8.0. That makes device compatibility worth checking before installation, particularly on an older family phone. The app is available at no cost, which lowers the barrier to trying it, but free access does not make personal financial information suitable for casual sharing.
For teenagers, I would treat the app as something to discuss rather than something to leave open for unsupervised exploration on a parent’s account. A parent might explain what credit is, why different people can have different profiles, and why login details stay private. The educational value comes from the conversation and the boundaries, not from handing over access to an adult’s account.
Trust works both ways. The account owner needs confidence that other household members will not browse private information, while other members need confidence that the app is being used for planning rather than monitoring them. I would make that agreement explicit on a shared device. “You can ask me about the household decision, but you do not need to inspect my account” is a healthier rule than leaving the boundary unspoken.
I also think this matters for roommates and extended families. Shared rent or bills do not automatically justify sharing credit information. If the app helps one person decide whether to take on an obligation, that person can communicate the practical outcome without exposing every underlying detail. Experian is most comfortable in a household when it supports consent-based coordination instead of becoming a tool for informal surveillance.
Version, maturity, and practical expectations
The current version is 4.2.28, and the app was released on May 12, 2016. I mention that because it shows this is an established finance app rather than a brand-new experiment, while the version number also reminds me to keep the app updated through the normal store process. Financial apps deserve a little more care than casual games: I would review the device account, notification behavior, and who can physically access the phone before making it part of a routine.
Experian has a 4.7 average from around 717 thousand ratings, with more than 200 thousand written reviews, and it has passed 10 million installs. Those figures suggest that many people have made it part of their financial routines, but popularity is not proof that it fits every situation. I would still judge it by the job I need it to do: credit awareness for one person, not complete shared budgeting for an entire household.
The app is free, which makes experimentation straightforward. Even so, I would not confuse a free download with a promise that every financial question will be answered inside one screen. Credit decisions can involve lenders, statements, payment records, and personal circumstances beyond any single app. My practical advice is to use Experian to organize what you need to investigate, then verify important decisions through the relevant account or official paperwork.
Who should use it and who should choose something else
I would recommend it to an adult who wants a convenient way to stay aware of credit-related information, especially before a major financial conversation. It also suits a household where each person is willing to maintain separate accounts and share only the conclusions needed for joint planning. The app is a good fit for someone who prefers short phone check-ins instead of waiting until a financial decision becomes urgent.
I would steer a person toward a budgeting app if their main goal is shared spending control. If the household needs joint categories, bill assignments, savings targets, or a running view of cash flow, a tool designed around those tasks will likely feel more natural. I would also choose a bank’s own app when the immediate need is checking transactions or confirming whether a payment has cleared. Experian should complement those tools, not be forced to replace them.
I would skip it as a primary solution if I am unwilling to keep financial access personal, if I want a complete investment dashboard, or if I expect the app to make complicated credit decisions for me. It can improve awareness, but it cannot remove the need for judgment. A clear screen does not automatically explain the best choice for a particular family, and a household conversation still matters more than a number viewed in isolation.
My household verdict
After using it as a focused credit-and-finance companion, I see Experian as a useful personal tool that can support better household coordination when its boundaries are respected. I like the free entry point, the established presence of developer Experian, and the fact that the app gives credit a regular place in my financial routine instead of leaving it until a major application appears.
My strongest recommendation is to keep the account personal, use the app with a specific question in mind, and bring only relevant decisions into the household conversation. On a shared device, privacy should be part of the setup from the beginning. Adults can coordinate goals without merging profiles, and younger family members can learn about credit without receiving access to someone else’s financial information.
In the end, I would install it for individual credit awareness and use a separate budgeting or banking tool for shared daily money management. That combination is more realistic than asking one app to do everything. If that division matches your needs, Experian is an approachable addition to a household finance routine; if you want a joint budget first and credit information second, another category of app will probably serve you better.
Pros
- Free credit score access with regular updates
- Credit monitoring alerts can flag suspicious activity quickly
- Personalized insights help explain changes to your credit profile
- Identity protection tools add useful security features
- Clean interface makes financial information easy to navigate
Cons
- Some advanced features require a paid subscription
- Offers for financial products may feel intrusive to some users
- Credit scores may differ from those used by lenders
- Identity monitoring coverage can vary by plan and location
- The app may request sensitive personal and financial information
FAQs for Experian®
What is Experian® used for?
Experian® is a credit and identity-management service that helps users review their credit information, monitor changes, and receive alerts about activity that may require attention. Depending on your country and subscription, the app may also provide credit-score education, personalized recommendations, identity-protection tools, and access to additional financial products. Available features can vary by region and account type.
Is the Experian® app free to download and use?
The Experian® app can generally be downloaded at no cost, and some basic services may be available through a free account. However, certain monitoring, identity-protection, credit-report, or premium financial features may require a paid membership or subscription. Before confirming enrollment, review the pricing, billing frequency, trial conditions, and cancellation terms shown in the app, since offers may differ by location.
Does using Experian® affect my credit score?
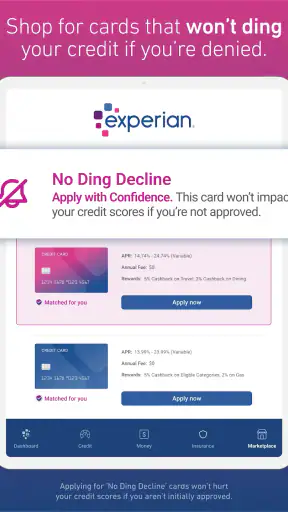
Checking your own credit information through Experian® is typically considered a soft inquiry and should not lower your credit score. Nevertheless, some products accessed through the app may involve applications for credit or other financial services, which could result in a hard inquiry if you authorize one. Always read the explanation provided before submitting an application or sharing information with a lender.
Is Experian® safe for personal and financial information?
Experian® is designed to handle sensitive identity and financial data using account-security measures such as encrypted connections, authentication controls, and fraud-monitoring features. Even so, no online service can guarantee complete protection from every threat. Use a strong, unique password, enable available security options, avoid logging in on unsecured public networks, and contact official support immediately if you notice suspicious activity.
What information is required to create an Experian® account?
Account registration commonly requires identifying details such as your name, address, date of birth, and information used to verify your identity. Experian® may request additional details, including government-issued identification or financial information, when accessing credit reports or identity-protection services. The exact requirements depend on your country and the feature you are using, so provide information only through the official app or website.

Experian®
This site provides independent information about third-party apps and is not affiliated with, or the owner, developer, or distributor of, any app featured here. App names, logos, and trademarks belong to their respective owners. Developer details are provided for reference; please contact the developer directly via AppSupport@experian.com, visit http://www.experian.com, or review their https://usa.experian.com/login/#/publicPrivacyPolicy.










